

What the US Midterms and South Africa’s Local Government Elections can mean for markets
While Europe and other parts of the world have long lived with proportional representation (PR) and coalition politics, other mature democracies with “first-past-the-post” (FPTP) systems had seemingly reached the stable equilibrium of a two-party state, with power oscillating over time between a centre-left and centre-right party. Branding was the only inconsistency, with UK Labour red and Tory blue the opposite of US GOP red and Democrat blue.
In recent years, however, increasing polarisation of politics is threatening the status quo as populist left and right insurgents vie for the public’s attention almost everywhere. The US is clinging to the two-party model, with MAGA and the DSA choosing to compete for control of the incumbent parties from within. In the UK, new parties have emerged instead, with the Greens attacking Labour from the left and Reform attacking the Tories from the right, raising questions over whether FPTP can sustain with the top four parties all currently polling between 14 and 23 percent. In theory, an outright majority might now be achieved by a party securing only around a quarter of the popular vote.
This picture of fragmentation is showing no signs of slowing down. In Europe, mostly right-wing parties are on the rise. They are feeding off increasing public opposition to an asylum system widely seen as an abuse of the expanded European Convention on Human Rights (ECHR), and both real and perceived impacts on culture, housing, crime and the ever-expanding cost of social welfare. Friedrich Merz’s CDU is under pressure in Germany as Alternative for Germany (AfD) is now the official opposition in the Bundestag. Macron in France faces a similar situation as his centrist coalition is challenged by Marine Le Pen’s National Rally which is polling in the mid 30’s percent ahead of 2027 elections. Sanchez in Spain is gambling on an early election to stave off the rise of Vox after 70,000 Moroccans illegally entered the Spanish enclave of Ceuta in July.
US Midterms: Trump becomes a liability
While Europe’s political challenges remain ahead, markets first need to navigate the US midterm elections, set to be held in early November. Contrary to trends across Europe and Latin America, the left is widely expected to stage a comeback.
By way of background, the US midterms is all about who controls Congress. The US Congress is the legislative branch of the US government and consists of two chambers – the House of Representatives and the Senate – both of which must pass a bill in identical form before it is sent to the President to be signed into law. The House is designed to reflect the popular will, with its 435 seats allocated in proportion to each state’s population and holds the exclusive right to initiate tax and spending legislation. The Senate, in which every state has two seats regardless of size (i.e. 100 total seats), is the more deliberative chamber and carries additional powers, including confirming senior presidential and judicial appointments and ratifying treaties. Which party controls each chamber therefore shapes both the laws that can be passed and the appointments an administration is able to make.
The House of Representatives is typically the most “in-play” chamber in the US midterms as all 435 seats come up for election every time, while only a third of the 100 senate seats are voted on, making it harder to flip. Midterms almost always lead to large losses in the House for the incumbent party, particularly where the sitting president has a weak approval rating entering the election. Only two elections in the last eighty years have produced a net gain in seats for the incumbent president. Bill Clinton achieved this in 1998 in the midst of very strong economic growth, and George Bush Jr in 2002 on the back of heightened concerns over terrorism in the wake of 9/11.
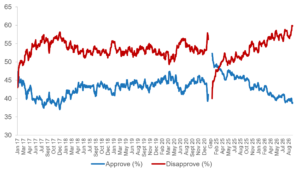
Given the narrow advantage the Republicans currently hold, and Trump’s approval rating falling by the day (Figure 1) it seems a near certainty that the Democrats take the House in November by netting the three seats needed. When it comes to US voters, the old catchphrase “it’s the economy, stupid” usually sums up the mood. While the economy and the stock market have held up well, this has been swamped by a new cost-of-living crisis brought on by the Iran war. Ford Broncos are being filled up at $5/gallon for the first time since Russia attacked Ukraine, diesel tractors and trucks at $6/gallon for the first time ever, and 30-year mortgage rates are back over 7%. Even Trump seems to sense the house is lost, reaching for a slightly desperate looking offer in a recent speech to pay every adult American $5,000 if the Republicans win both houses.
Figure 1. Trump approval/disapproval ratings (both terms)
Source: Real Clear Politics, Bloomberg
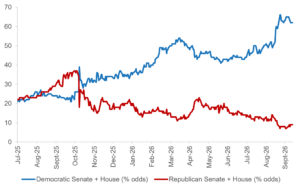
The four additional seats needed (on top of winning their 13 seats up for re-election) to flip the Senate will be tougher given the smaller number of seats up for grabs, but here too sentiment seems to be shifting. In recent months polls have consistently suggested a race too close to call, however in recent days polls and prediction markets alike have tilted towards a “blue sweep” (Figure 2). In reality though, the Senate probably remains a coin-flip and a divided Congress remains a high probability.
While the Republicans could possibly lose both houses of Congress, one should be careful not to overstate the implications. President Trump has certainly shown scant regard for the House, choosing instead to govern by executive order. He has signed a total of 508 so far at the halfway mark of his second term, compared to 277 in total for Obama through two full terms.
While some checks will indeed emerge on Trump’s powers, the Presidential Veto means that even in the case that he loses the House and the Senate, the Democrats will still need White House cooperation to pass any new laws. The veto can only be over-ridden with a two-thirds majority which neither side is likely to achieve.
Figure 2. Polymarket probability of House + Senate win
Source: Polymarket, Bloomberg
One of the most likely consequences of a blue sweep will be on President Trump’s ability to make executive branch appointments. His long-running campaign to reshape the FOMC will become increasingly difficult given the need for Senate confirmation of candidates, for example should former Fed Chairman Powell decide to finally step down as has been the custom from other former chairs.
Another implication will be a shift in the balance of power in negotiations ahead of the FY2027 budget. Trump’s Department of War has requested a 44% (+$440bn in one year) increase in defence spending (on top of last year’s 17% increase), while the Democrats remain vehemently opposed to the +$1trn of Medicaid cuts over the next ten years introduced by the One Big Beautiful Bill Act. Rather than a check on fiscal profligacy, a compromise will have to be reached between two deficit negative priorities. The current US government debt ceiling of $41trn is likely to be breached around the middle of 2027, setting markets up for the potential of another protracted government shutdown.
From an equity standpoint, the midterms may represent the beginning of the end to a period of soft-touch regulation for certain sectors. Trump recently personally oversaw a “voluntary accord” between the top US AI companies to “self-regulate” the technology. Crypto companies have seen the SEC rushing to rewrite securities rules to make it easier for investment advisors to hold Crypto assets on behalf of their clients despite the “Clarity Act” struggling to gain approval in the Senate. Big Tobacco has seen the FDA chief ousted over his opposition to flavoured vapes, leading to a loosening of marketing and enforcement restrictions on nicotine products in general. A democrat-controlled Congress would most likely seek to become more interventionist in some of these areas.
All this being said, a divided Congress, with the Democrats taking the House and Republicans retaining the Senate, is generally seen as broadly market friendly and such an outcome has generally coincided with positive market outcomes in the past.
SA Politics: Coalitions are here to stay
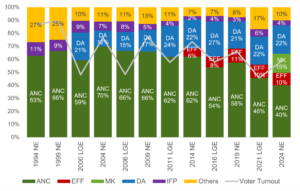
Turning to South Africa, FPTP infamously led the National Party to power in 1948 with only 37.7% of the vote, invariably leading to a shift towards PR in the new constitution agreed to at the end of Apartheid. However, since then the ANC’s dominance has meant a single party state for thirty years. The first sub-50% outcome for the ANC in the 2021 Local Government Elections (LGE), and subsequently in the 2024 National Elections, led to the formation of the GNU (Figure 3) and the ushering in of coalition politics. While the GNU would probably be described as a “qualified success” to date, municipal coalitions have become increasingly chaotic.
Figure 3. South Africa Election results
Source: IEC
In the upcoming 2026 round, scheduled for the day after the US midterms, the ANC is widely expected to continue its gradual slide. The intrigue, however, is more likely to come from opposite ends of the risk spectrum.
The MK Party’s (MKP) first local government election is a focus point. MKP secured 45% of the KZN vote in the 2024 national elections but were kept from power by the ANC/DA/IFP coalition. Polling ahead of this local election suggests they may well end up controlling a significant portion of KZN’s municipal budgets either outright or in coalition with like-minded parties such as the EFF. For obvious reasons this evokes memories of the state patronage of the Zuma years. While their overall role is likely limited nationally, they may well also play a kingmaker role in certain parts of Gauteng. Any outperformance beyond this would be unsettling to investors.
And then to the prospects for the DA. Whilst certainly not devoid of shortcomings, the one edge they hold over other parties is their demonstrable track record of sound governance in the Western Cape. Despite this they have largely found their support capped just above the 20% level, after peaking at 26.9% in the 2016 LGE. This is likely a seminal election for them to demonstrate that they can begin to attract voters away from other parties on the promise of less corruption and greater service delivery. They certainly have talked up their prospects in this regard, with a publicly stated target of increasing the number of municipalities they govern from 27 to 60 and floating the possibility that they may emerge as the largest party in every major metro in the country. Anywhere near this sort of progress would conversely be celebrated by investors, especially in the economic hub of Johannesburg which has become the poster child of municipal decay.
Voter turnout, a record low of 45.8% in 2021, and the number of hung councils (66 in 2021, more than double that of 2016) will be key to watch. As mentioned above, municipal coalitions have proved to be extremely unstable in SA, leading to the proposed Coalitions Bill which will, amongst other reforms, introduce a 1% electoral threshold for council seats and restrict no confidence motions to once every 12 to 24 months. Unfortunately, promulgation is only likely after this election, so those improvements are for the future. South Africa’s democracy nevertheless continues to mature, with all parties having more experience with coalitions. Hopefully this translates into more stable combinations and less of a role for opportunist parties looking to leverage their positions for power. Markets will be watching for signs of GNU stability.
Conclusion
Taken together, these contests point to a broader shift: the two-party and single-party certainties of the past are giving way to more fragmented, coalition-driven politics across much of the democratic world.
For markets, the near-term read is reasonably benign – a divided US Congress has historically been market-friendly, and a maturing South African coalition landscape holds the promise of greater stability over time.
The more important question is a longer-term one: whether these more fractured systems can still deliver coherent, disciplined policy, or whether government by compromise simply entrenches fiscal drift.
For now, we would caution against overstating the immediate implications of either vote, while watching closely the signals that matter more over the medium term – the US fiscal negotiations and looming debt ceiling on the one hand, and the stability of South Africa’s coalitions on the other.
